

Benefits OnLine

- 1.06K Reviews
- 3.5
- Downloads
- 1,000,000+
Our take on Benefits OnLine from Appgk
Benefits OnLine is a finance app focused on retirement and workplace benefit services from Merrill Lynch, Pierce, Fenner, and Smith Inc. I see it as a practical companion for people whose employer already uses Merrill’s benefits platform, rather than a general-purpose money manager for everyone. Its first impression is fairly clear: this is meant to put benefit-related information in one place so you can check it when a work decision, enrollment task, or retirement question comes up.
The app is free, carries an Everyone age rating, and has passed the point where it feels like an untested newcomer. It was released on October 1, 2018, and the current version is 26.08.02 for devices running operating system 11 or later. With more than a million installs, it is clearly used beyond a small group of early adopters. Still, its average rating of 3.5 from roughly 3,400 ratings suggests a mixed everyday experience rather than universal enthusiasm.
What Benefits OnLine feels like in the first week
During the first week, the main appeal is convenience. Retirement and benefit details are not information most people want to search for every day, but they become important at very specific moments: starting a new job, changing a contribution, reviewing a beneficiary, preparing for enrollment, or trying to understand what is available through an employer. Having a dedicated mobile entry point can be easier than remembering where a benefits portal lives or opening a desktop browser.
I would not approach this as an app I expect to explore for entertainment. Its value depends on whether my employer’s retirement or benefit arrangement is connected to the Merrill service. That distinction matters. A person looking for budgeting, bill tracking, bank aggregation, or broad investment research may open it and quickly realize that it is not designed to replace those tools.
Best Parts of Benefits OnLine
Things to Keep in Mind About Benefits OnLine
The strongest early use case is a focused check-in. I can imagine opening it before a conversation with human resources, looking over retirement information before deciding whether to adjust a workplace contribution, or checking details while away from a computer. That makes the app useful in short sessions. It does not need to become a daily habit to justify its place on a phone.
At the same time, the first-week experience is likely to be shaped by access rather than by the app alone. Benefits platforms depend on the employer relationship and the account information attached to it. If I do not have an eligible workplace connection, the app has little reason to remain installed. This is the first important trade-off: the service can be highly relevant to one employee and almost irrelevant to another person standing beside them in the same app store.
News and Features Related to Benefits OnLine

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Who gets the most from it
I would recommend trying Benefits OnLine first if your employer has directed you to Merrill for retirement or benefit services. It is especially suitable for employees who prefer checking information on a phone, people who do not regularly use a laptop for administrative tasks, and anyone who wants a quick way to revisit workplace benefit details between larger decisions.
It may also help employees who are easily overwhelmed by financial paperwork. A dedicated app can make a recurring administrative task feel more approachable than a folder of documents or a long series of browser bookmarks. The important point is to use it as an information and account-management aid, not as a substitute for understanding the choices themselves.
Don't want to read the full review?
I would skip it if I wanted a complete personal-finance dashboard or an independent retirement planner unrelated to an employer benefit program. A budgeting app is usually better for spending categories and household cash flow. A brokerage app may be better for people managing their own taxable investments. A retirement calculator can be better for testing hypothetical savings plans. Benefits OnLine has a narrower job, and that narrowness is part of its usefulness.
A realistic everyday scenario
Imagine an employee who receives a reminder about workplace enrollment while commuting home. Instead of waiting until the next time they use a computer, they open the app, review the relevant benefit information, and make a note of what still needs clarification. Later, they can speak with human resources or a financial professional with more specific questions. In that situation, the app does not make the decision for them; it reduces the friction between receiving information and acting on it.
Screenshots
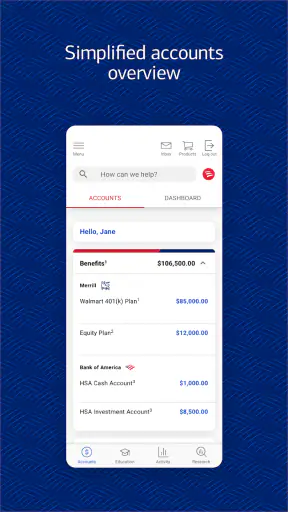
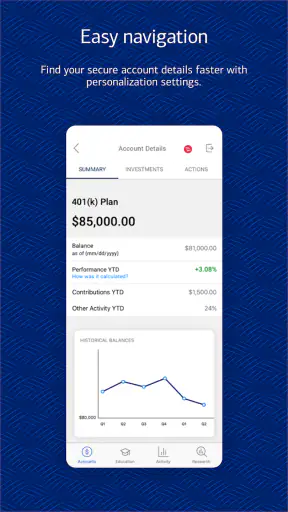
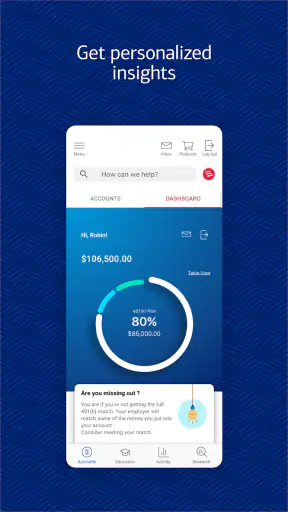
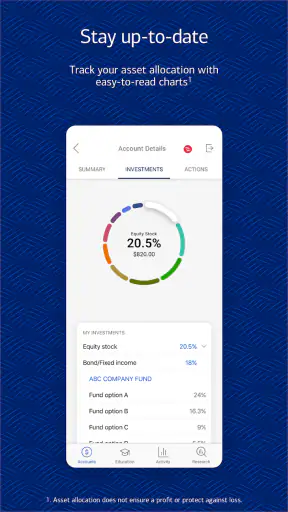
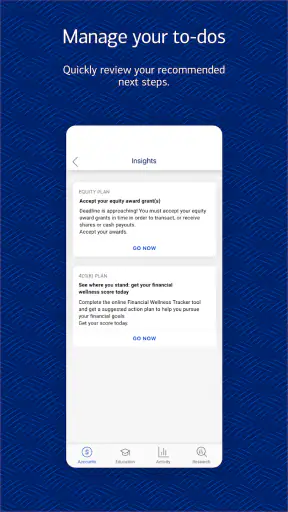
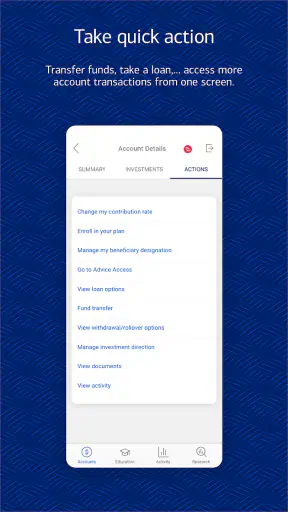
That is the kind of recurring value I find believable here. The app is most helpful when it shortens the distance between a life event and the benefit information connected to it. It is less compelling when I expect it to offer constant financial guidance or a stream of new insights.
How the value holds up after the novelty fades
Month-to-month usefulness is event-driven
Benefits OnLine is not naturally a high-frequency app. Most users will probably not need to open it several times a day, and forcing that kind of routine would make little sense for retirement administration. Its month-to-month value comes from being available when circumstances change: a new job, a benefits window, a contribution decision, a change in family situation, or a desire to review long-term planning information.
I think that is a healthier pattern than treating every finance app as a dashboard that demands constant attention. Retirement decisions should not be made impulsively just because a notification or a colorful chart appears. A tool that supports deliberate check-ins can be more appropriate than one that encourages constant tinkering.
The downside is that an app with event-driven value can feel forgotten between those moments. If I install it during enrollment and then do not need it for months, its presence on the home screen may start to feel unnecessary. The answer is not to invent reasons to open it. Instead, I would keep it installed only if I expect to use it for future benefit reviews or if access to timely workplace information matters to me.
Three habits that make it more useful
My first practical tip would be to use the app before a benefits conversation, not during a rushed deadline. Reviewing the information early gives me time to write down unfamiliar terms and separate questions about eligibility from questions about investment choices. That small preparation step can make a short conversation much more productive.
Second, I would treat the app as a checkpoint rather than the sole record of an important decision. For major retirement or beneficiary changes, I would make sure I understand what was changed and keep any confirmation or personal note that helps me remember the decision. The app can make access easier, but convenience should not replace careful record-keeping.
Third, I would review information after a major personal change instead of waiting for an annual reminder. Marriage, divorce, a new dependent, a job transition, or a change in household priorities can all be reasons to revisit workplace benefits. The useful insight here is that the app’s value is tied less to a fixed schedule than to the moments when my circumstances change.
Where it compares well with alternatives
Compared with a desktop-only benefits portal, a mobile app can be more convenient for quick checks and easier to reach when I am away from a desk. Compared with a general finance app, it is more directly connected to employer-provided retirement and benefit information. That specialization is its clearest advantage.
Compared with a full financial-planning service, however, Benefits OnLine is likely to feel limited for someone who wants one place to combine bank accounts, debts, spending, outside investments, and long-term projections. A general app may offer a wider household view, while this one is better suited to the workplace benefits relationship. I would use both when their purposes differ, rather than expecting one to replace the other.
The same comparison applies to advice. A general retirement tool may be more flexible for experimenting with assumptions, while a workplace benefits app is more relevant to the actual program attached to my employment. The better choice depends on whether I need broad planning or access to a specific benefit account.
Maintenance, friction, and the reasons users may tire of it
The maintenance burden is low, but not zero
The app does not need constant attention to remain useful, yet financial information should not be treated like a permanently finished task. I would keep the operating system compatible, install the current app version when appropriate, and check access before an important deadline rather than discovering a login problem at the last minute. Those are simple habits, but they matter more here than frequent browsing.
Because the current version is 26.08.02 and the minimum operating system is 11, device age can affect whether the app fits comfortably into a user’s routine. Someone using an older phone may need to think about compatibility before relying on it as the only way to reach benefit information. I would keep an alternative route available for urgent matters, especially during an enrollment period.
Account access is another maintenance concern. Workplace services can become less relevant after changing employers, and a person may not want to keep an app that no longer connects to their current benefits. That is not a flaw unique to mobile software, but it does affect long-term retention. The app earns its space when the employer relationship remains active and useful.
What creates fatigue
The biggest source of fatigue is probably the mismatch between occasional need and permanent app presence. If I rarely review retirement information, I may forget why I installed it. A second source is the seriousness of the subject. Benefit language can be dense, and a mobile screen does not automatically make complex choices easy. The app can improve access without making every decision simple.
There is also a psychological limit to convenience. Opening an account on a phone may be quick, but deciding what a retirement option means can still require time, documents, and advice. I would be cautious about making a change merely because the interface makes it easy to reach the relevant screen. The best workflow is to use the app for preparation and review, then slow down for decisions with long-term consequences.
The mixed average rating of 3.5 is worth keeping in mind. It does not tell me exactly which experience each person had, but it does suggest that access and usability may not feel equally smooth for everyone. I would judge the app after trying it with my own employer connection, device, and account rather than assuming that a large install base guarantees a perfect experience.
Privacy and decision boundaries
Retirement and benefit information is personal, so I would use ordinary phone-security habits: a screen lock, updated software, and care when accessing the account on shared or public devices. I would also avoid discussing sensitive account details in screenshots or messages unless I had a clear reason to do so.
Most importantly, I would separate viewing information from receiving advice. Benefits OnLine can be useful for seeing what is associated with my workplace benefits, but I would still read the relevant explanations and ask qualified questions when the decision is complicated. That boundary keeps the app in its proper role and reduces the risk of treating a convenient screen as a complete financial plan.
My long-term verdict on Benefits OnLine
After the novelty fades, I think Benefits OnLine earns a lasting place for the right employee, but not as a universal finance app. Its recurring value comes from being a dependable access point for Merrill workplace retirement and benefit services when a real need appears. That may happen only occasionally, yet those occasions can be important enough to justify keeping it available.
I like the focused purpose. The app does not need to compete with budgeting tools, banking apps, investment marketplaces, or broad planning software when its job is to support a specific benefits relationship. For someone whose employer uses that relationship, the focused design can be more useful than a crowded financial dashboard filled with unrelated accounts.
I would be less enthusiastic for a person who wants daily motivation, detailed household budgeting, independent investing, or a complete retirement forecast. Those users should look toward tools built around those tasks. Installing this app will not solve a lack of financial understanding, and it should not be mistaken for professional advice.
My final recommendation is simple: if Merrill’s workplace benefits service is part of your employment, try Benefits OnLine and keep it if it saves you time during reviews, enrollment, or important life changes. Set it up before you need it, learn where the relevant information lives, and use it as a preparation tool for thoughtful decisions. If you have no connection to its retirement and benefit services, the app is unlikely to offer enough independent value to remain on your phone.
For its intended audience, the free price and broad availability make trying it low-risk, while the Everyone rating makes it suitable for a general audience. Its lasting strength is not novelty or constant engagement; it is the practical reassurance of having workplace benefit information close at hand when the moment calls for it. That occasional, purpose-driven usefulness is the reason I would recommend it selectively rather than universally.
Benefits OnLine FAQ
What is Benefits OnLine and who can use it?
Benefits OnLine is a digital platform that helps eligible employees, plan participants, and account holders view and manage workplace benefits, retirement savings, investments, and related financial information. Access depends on the employer, financial institution, or plan administrator that provides the service. Before downloading, confirm that your organization supports Benefits OnLine and that you have valid registration details.
What can I do with the Benefits OnLine app?
After signing in, the app may allow you to check account balances, review contributions, monitor investment performance, view transaction history, access statements, and manage certain personal or plan settings. Available tools can vary depending on your employer-sponsored plan and account permissions. Some actions, such as changing investments or beneficiary information, may require additional verification.
Is Benefits OnLine safe for viewing financial and benefits information?
Benefits OnLine is designed for handling sensitive benefits and financial account data, so it generally includes security measures such as encrypted connections, secure login procedures, and account verification. Users should still protect their credentials, avoid signing in over unsecured public networks, and enable any available biometric or multi-factor authentication. Never share passwords or verification codes with anyone.
Why can’t I log in to Benefits OnLine after downloading it?
Downloading the application does not automatically create access to an account. You usually need to register with information connected to your employer or benefits plan, then provide a username, password, and possibly a verification code. If your organization recently changed providers, your account is inactive, or your details are incorrect, contact the plan administrator or use the official recovery options.
Is Benefits OnLine free to download and use?
The Benefits OnLine application is typically available to download without a separate app purchase, but the benefits, retirement, or investment accounts shown inside it are governed by your plan’s terms. Depending on the account, investment choices, transactions, or other services may involve fees. Standard mobile data charges may also apply, so check your provider’s documentation for complete cost information.











